
Written by: Corey Janoff
This post was originally published on our previous blog website on July 25, 2018 and has since not been revised and/or updated.
My clients who are in the best financial shape are also my most boring clients. Their personalities aren’t boring – far from it. They’re all very nice people and enjoyable to have a conversation with. Their finances though are quite boring. And that is a compliment.
There are many adjectives you could use to describe one’s financial state. Exciting, great, dismal, worrisome, anxious, erratic, static, complex, exhausting, daunting, to name a few. If you want to have a sound financial picture, shoot for boring.
If you always have something new going on with your finances, odds are it’s not all beneficial to you. New home, new job, new car, new business opportunity, unexpected expenses, loss of job, investment that didn’t pan out, etc. I understand that some of these things are out of your control. Luck does play a role in everyone’s life. Some people are luckier than others. However, you can also plan for unexpected expenses and a job loss by having an adequate emergency fund. Other items that many people would consider exciting, often involve transactions costs that can put a temporary halt on your financial goals.
When it comes to investing, if you are swinging for the fences with every investment you make, the home runs may not be sustainable. If you have a few unsuccessful bets, it could seriously set you back and prevent you from reaching your goals in a timely manner. I have seen many clients invest in high risk, high reward opportunities. Most lost their entire investment and never received anything in return.
Those types of investments are fine if you are prudent with how you go about it. Only use excess money after all of the monthly/yearly funding for your financial goals have been met. That way, if you lose it all, it doesn’t affect your overall financial goals. If you do get lucky and hit the home run, then that will only accelerate your path to financial independence.
Rather than constantly looking for greener grass, be boring and make the grass you have as green as possible.
Simplify
My clients who have the most success at achieving their financial goals have the simplest financial picture. They own one house. The mortgage balance is less than two times their income. They drive boring cars that are either paid off or carry low monthly payments in relation to income. They only have a few investment accounts. They usually only invest in mutual funds and exchange-traded funds (ETF’s). They buy and hold for the long run and rarely place trades other than to rebalance the account once or twice a year.
I do have some successful clients who have a portfolio of real estate investment properties, but those clients are few and far between. Successful real estate investing isn’t as easy as it looks on TV. Find a low-maintenance property that you can rent to respectful tenants for a considerably higher price than it costs you. Easier said than done.
One of my favorite clients is a retired couple who has a seven-figure portfolio yet doesn’t spend any of it. Their Social Security checks are enough to support their lifestyle. When they receive their required minimum distributions from their tax-deferred retirement accounts each year, I have to encourage them to spend the money. I have to fight with them, because they always tell me they don’t need it and want to reinvest it.
Now, that example might be a little extreme, but it is simplicity at its finest. They go on vacations. They go out to dinner. They have season tickets for their college football team. They enjoy life. They just live such simple lives that it doesn’t cost a lot of money.
My boringly successful clients keep it simple. They rarely have any changes in their lives. They spend less than they earn. They save a portion of every single paycheck for their retirement and other financial goals. They reach out to me anytime they have questions about their finances and they follow my advice.
Follow a Plan
Your financial plan should be boring. What I outlined in the previous paragraph should perfectly summarize your financial strategy.
Thanks to 24/7 news cycles and excellent marketing by discount online brokerage companies, some people believe that you have to constantly be paying attention to the markets and make frequent adjustments to your investment portfolios in order to achieve success. Pretty much every study conducted on trading frequency concludes that the more often you trade an account, the worse you do.
For one, you can’t time the market. You’re delusional if you think you can. If people could time the market, why didn’t we all get the memo that some of the largest banks in the history of the world were going to collapse in 2008?
If you are reading this blog, there is an extremely high probability that you are an amateur investor at best. Remember, every time you place a trade, there is someone on the other end of that trade who has the opposite conviction as you. If you sell a particular stock because you think it has reached its peak, the person purchasing the stock from you believes it is a good buy. Same when you buy a stock – the person on the opposite end is dumping it from their portfolio. Odds are, that “person” on the other end of the transaction is a computer algorithm created by MIT and Harvard alumni who are employed by a large institutional investment company with a high eight-figure research budget. Translation: they know more than you.
Rather than watching the news, reading articles, and monitoring your investments daily, go do something more enjoyable. Spend time with your family. Go on a hike. Watch a new TV show. Read a book (preferably fiction).
Create a boring financial strategy where you invest in a diversified portfolio of boring mutual funds and/or ETF’s and only look at it once or twice a year to rebalance back to your target investment mix.
Other studies have been done that conclude the less frequently you look at your investment accounts, the better off you do.
Avoid Temptation
There is an endless chorus of sirens in the world attempting to lure you into giving them your money. Lavish vacations. Vacation homes. Timeshares. Luxury cars. Fancy restaurants. Business ventures. Charities. Subscription services. Home maintenance services. Department stores – can’t miss the anniversary sale! Black Friday. Prime Day.
Keeping up with the Jones’s is a serious illness. We all do it to some degree. We spend money on stuff we don’t need to impress people we don’t care about.
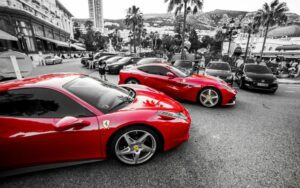
When was the last time you saw someone driving a Ferrari and thought to yourself, “Wow, that guy driving the Ferrari must be really cool?” Probably never! The more likely thought to pop in your head when you saw the Ferrari was, “I want a Ferrari. If I had a Ferrari, people would think I’m really cool.” I’ve never been in one, but I’m sure driving a Ferrari would be awesome. However, people won’t think you are cool because you drive a Ferrari. They either won’t think anything of you, or they will think you are overcompensating for something.
Spending money on unnecessary things is fine if you do it in moderation and you can afford to do so. “Afford to do so” doesn’t mean you have enough money in your bank account or a high enough limit on your credit card. It means you are on track to reaching all of your important financial goals and you have extra money left over that you can blow on whatever you want.
Everything in moderation. I love pizza. And cheeseburgers. And beer. And wine. And bourbon. But if I only eat pizza and cheeseburgers and drink alcohol, my health probably won’t be that great.
Running is supposedly good for you. But if you run 50 miles a week, your joints will probably break down and you will be crippled in your old age.
In Conclusion
Be boring with your finances. You may not become an Instagram sensation. You may not be able to brag at the water cooler about the hot stock you bought that tripled in value over the last year. But your net worth will stand taller than your peers and financial independence will be a reality for you one day.
Disclosures:
All investing involves risk. Depending on the types of investments, there may be varying degrees of risk. Investors should be prepared to bear loss, including total loss of principal.