Written by: Corey Janoff
This post was originally published on our previous blog website on December 6, 2017 and has since not been revised and/or updated.
It has been almost a decade since I began helping people plan and manage their finances. I have met with and reviewed finances for close to 1,000 individuals and families and I have worked with hundreds of clients over a multi-year span. In meeting and working with people, I have picked up some general observations about how money affects people and how different types of people view money. In this post, I will review some of the things I have noticed over the years.
By no means is this list complete or absolute, nor is it good or bad. I haven’t done any hard research or data analytics to determine if the evidence is significant and conclusive. It is merely some general themes I have observed that I believe apply to the majority of people. Let’s dive in.
Above Average Goals Require Above Average Effort
People that are willing to put in the extra effort are the ones that are able to do the extraordinary. Sports is a great example of this. The top athletes/teams are the ones that usually outwork the competition.
Take Tom Brady for example. The dude eats, sleeps, and lives football. Every second of his life is calculated. If it doesn’t help make him a better football player, he won’t do it. He has five Super Bowl rings to show for his dedication and is showing no signs of slowing down on the field as a 40-year-old.
Michael Jordan’s practice and workout habits were legendary. He was one of the first basketball players to lift weights regularly. He was one of the first athletes to hire a personal trainer. The guy practiced basketball year-round at a time when many professional basketball players still treated it as a seasonal job.
Tiger Woods took the golf world by storm when he applied Michael Jordan’s work ethic and tenacity to the golf course. The whole, is-golf-a-sport/are-golfers-athletes debate was put to rest when El Tigre showed up in the late 1990’s.

Many people say they want to do outstanding things, or accomplish lofty goals, but are not willing to put in the time and effort necessary to achieve greatness. Actions speak louder than words.
If you want to retire in your late-40’s or early 50’s, you need to save and invest for retirement more aggressively than someone who plans to work into their mid-60’s. Think about it. If you start really working and saving in your late-20’s to early-30’s and you plan to retire in your late-40’s to early-50’s, you only have 20 years to save for retirement, compared to someone who typically has around 35-40 years of a working career to save. On top of that, if your life expectancy is around age 90, you now have a 40 year long retirement to pay for, whereas the “average” person only has about a 25 year retirement. So you have less time to save enough for a bigger need. This requires above average commitment and dedication to investing for retirement. If you can save an above average amount, you can potentially retire sooner than average, and/or live an above average lifestyle in retirement.
“Keeping up with the Jones’s” is a Real Phenomenon
I see this all of the time. People feel the pressure to live in a similar type of neighborhood as their peer group, drive the same type of car as their peers, go on similar vacations as their peers, eat at the same restaurants, shop at similar stores, etc. The list goes on.
If you move into a nice neighborhood, you don’t want to be “that guy” driving the beater car and still assembling mismatched Ikea furniture. We feel internal pressure to spend money on the same things as the people we associate ourselves with. We live in a society where people are judged on appearance. Do you look the part? Do you really belong in this circle?
As a financial advisor, if I show up to meet a prospective client wearing tired jeans and a stained t-shirt, that person is probably not going to become a client. A suit and tie, or slacks and a button-down shirt would be more apropos. I don’t necessarily need to sport a custom-made designer suit that sets me back a pretty penny, but a clean outfit that fits me is necessary.
We are told to judge people on the content of their character, but our minds don’t always work that way. Malcom Gladwell details in his book, Blink, how our minds subconsciously make rapid decisions. Within 30 seconds of meeting someone, you have pretty much made up your mind as to how you feel about this person, so first impressions are key.
There is No Such Think as Too Much Money
Money doesn’t buy happiness, but it can buy a lot of things that make you happy. And there is no shortage of things you can spend your money on.
I have worked with some clients since the beginning of their careers when they were making less than $50,000/year. Most of them were doing just fine at that income level. They were able to afford their housing costs, food, and save a little bit for retirement. Today, some of them are earning upwards of $500k, $600k, $700k, even $1,000,000 per year. And you know what? A lot of them feel pressure to earn more money, because they can’t afford all of the things they desire in life.
Once the income rises, many people will buy the bigger house, buy nicer furniture, purchase or lease the nicer (more expensive) cars, possibly send their kids to private schools, go on nicer vacations, stay in nicer hotels, maybe purchase the vacation home, eat at nicer restaurants, join the country club, buy the boat, partially support some family members who aren’t as fortunate, and pay less attention to where their money is going.
They realize they are spending a lot of money on these things and also realize that they need to save more money if they are going to continue living that lifestyle. So they work harder to earn more money, which enables them to spend more, which puts more pressure on them to save more, and the cycle continues.
Why do so many celebrities end up bankrupt? Why do so many wealthy politicians end up misappropriating funds for their own personal benefit?
While you will ALWAYS find a way to put money you have to use, it is up to you to determine the best way to use that money. If you make sure to pay yourself first, before spending money on things you don’t really need, then you will be able to sleep soundly at night. Make a plan. How much to you need to set aside each year/month/week, to enable you to reach your financial goals? Ok, do that first. Then with what’s left over, go nuts and don’t feel bad about going nuts.
Cost of Living Affects Financial Goals
I think everyone is aware of this one, but not everybody is willing to accept it. If you earn $100,000/year and spend $30,000/year on housing, that puts you in a more difficult position that someone who earns $100,000/year and spends $12,000/year on housing. That’s an $18,000 difference (after-tax for the most part). That is your retirement savings right there. That is your kids’ college savings. That is all of those international vacations you want to take.
Cost of living is a game of simple economics: supply and demand. A lot of people want to live in certain parts of the country, therefore real estate prices, taxes, and cost of goods in those areas is higher than other areas of the country. You want to live in Los Angeles because the weather is nice and there is so much to do? So do 20 million other people. But there is only room for about 4 million people. So you are going to have to be willing to pay more than 16 million others if you want live there.
You want more affordable housing? Move to Iowa City, Iowa. Oklahoma City, Oklahoma. Wichita, Kansas. Fayetteville, Arkansas. Fargo, North Dakota. Waco, Texas. You can buy a house for a fourth of the cost (or less) in these places as you can in some of the major metropolitan cities on the coasts. And quality of life is just as good.
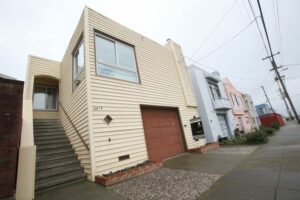
$1,000,000 in San Francisco, CA
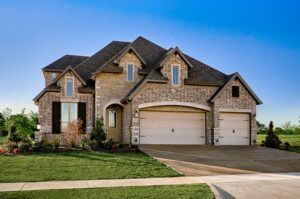
$400,000 in Fayetteville, AR
People in the Midwest seem to be happier, kinder folks. Probably because they aren’t grumbling and kicking themselves every day for choosing to live in an overly crowded, expensive city, where they spend an hour commuting each way to and from work. No, there isn’t a top musical artist or group performing each week. There isn’t a professional sports team playing each season. There is no such thing as “bottle service” at the bars/clubs. But there are still bike trails, golf courses, parks, rivers, and lakes. Cable, internet, and cell phone service runs in most of the cities in the flyover states.
Plus, certain professionals end up earning a lot more income if you work in those “less-desirable” cities. I have some physician clients who live in the Midwest and earn 2-3 times the national average for their specialties.
If you can earn the same or more than you would in a big city and cost of living is a fraction of what it is in a big city and you don’t feel the same pressure to keep up with the Jones’s, reaching your financial goals will be a lot more doable.
Life is What You Make of It
It doesn’t matter how much you make, or where you live. Your life and your happiness is dependent on you and the people you surround yourself with. I know a pharmacist who earns about $125,000/year, has a wife and two children at home, lives in a modest house, saves a healthy amount for retirement, and is happy as a clam. I also have several clients who make upper six figures and are constantly stressing about money.
Ask yourself, what truly makes you happy? I would be willing to bet it’s not material things. Is it spending time with loved ones? Is it sitting in your favorite chair, reading a book? Is it going for a walk in nature? Now ask yourself, what can you do focus more energy on the things that make you happy? And how can you structure your finances to enable you to do just that?